The Future of Digital Banking in Bangladesh
Branchless digital banks, Bangla QR, person-to-person QR transfers and better bank apps are reshaping how Bangladesh banks. What is coming, who the players are, what could go wrong, and what it means for you.

Short answer: The future of digital banking in Bangladesh will be shaped by four forces: the first branchless digital banks, five of which received initial approval in September 2026, including bKash Digital Bank and Robi-backed Boost; Bangla QR, now a single payment code at about 39 lakh merchant points, with person-to-person transfers set to follow; better bank apps from traditional banks under pressure; and new payment players such as Banglalink’s Mukto Pay. Bangladesh Bank wants 75% of retail transactions to be digital by 2027. The big risks are trust, fraud, weak digital literacy, banks’ bad loans and slow regulation, and about 75% of bank customers still use no digital service at all.
A bank account without a bank
Sumi, 23, sells handmade jewellery through a Facebook page from her home in Sylhet. She has used bKash for years, but she has never had a bank account. The nearest branch is a bus ride away, and the one time she went, she was told to come back with more papers. “I do all my business on my phone,” she says. “Why can’t my bank be on my phone too?”
That is exactly the customer Bangladesh’s coming digital banks hope to win.
Where does digital banking stand today?
| Indicator | Latest figure |
|---|---|
| Banks offering internet banking | 58 of 61 |
| Bank app users | 85.7 lakh (November 2025) |
| Bank customers using no digital service | About 75% (BIBM study) |
| Adults with a bank account | 28.3% |
| Adults with a mobile money (MFS) account | 47.8% |
| Bangla QR merchant points | About 39 lakh (September 2026) |
| Daily Bangla QR payments | About Tk 143.5 crore (September 2026) |
| Bangladesh Bank target | 75% of retail transactions digital by 2027 |
Sources: Bangladesh Bank data reported by The Daily Star and UNB; BIBM study reported by The Financial Express; account ownership figures cited by The Daily Star.
The picture is a country where more people trust a mobile wallet than a bank, and where digital payments are surging while most bank customers still bank the old way.
What is a digital bank?
A digital bank is a fully licensed bank that has no branches. It runs from a single head office and serves customers entirely through an app and digital channels. Under Bangladesh Bank’s rules, a digital bank needs paid-up capital of Tk 300 crore, raised from Tk 125 crore, and must hold an IPO within five years of getting its licence, The Daily Star reported. That is different from a bank app, which is simply a digital channel of a branch-based bank, and from a mobile wallet such as bKash or Nagad, which is not a bank.
| Traditional bank | Digital bank | Mobile wallet (MFS) | |
|---|---|---|---|
| Branches | Yes | No (head office only) | Agents, no branches |
| Full bank licence | Yes | Yes | No |
| Savings and deposits | Yes | Yes | Wallet balance only |
| Loans | Yes | Yes, through the app | Limited, often through partner banks |
| Main channel | Branch, then app | App only | App, USSD and agents |
Who will run Bangladesh’s first digital banks?
The road so far has been bumpy. In 2023, Nagad Digital Bank and Kori Digital Bank got the first letters of intent, but neither launched. Nagad’s licence was later suspended, and Kori failed to meet the conditions in time. A World Bank Group report said that first selection lacked transparency and showed favouritism towards politically connected interests, The Business Standard reported.
Bangladesh Bank reopened applications in 2025 and received 12 new applications. On 24 September 2026, its board gave initial approval to five, The Business Standard reported:
| Proposed digital bank | Backers |
|---|---|
| bKash Digital Bank | bKash shareholders |
| Boost Digital Bank | Axiata, parent of Robi |
| Nova Digital Bank | VEON, parent of Banglalink, and Square Group |
| DK Digital Bank | DK Bank of Bhutan |
| Kori Digital Bank | Fresh approval after missing the first deadline |
These are letters of intent, not final licences. Each must build its technology and pass Bangladesh Bank’s checks before it can open to customers. Because two of the five are backed by mobile operators and one by the country’s largest mobile wallet, they start with millions of existing users, which could let them grow much faster than a new branch-based bank ever could.
What will change for customers?
Nobody knows exactly what Bangladesh’s digital banks will offer until they launch. But based on how digital banks are designed and what existing apps already do, customers can expect:
- Opening an account from your phone with your NID and a selfie (e-KYC), with no branch visit.
- Small loans based on your digital history, such as mobile payments and sales records, rather than collateral. This could help people like Sumi and small shop owners who are shut out today. See why Bangladesh needs more financial startups.
- Lower costs. A BIBM study estimated a branch transaction costs a bank Tk 90, against Tk 1.74 for internet banking, The Business Standard reported. Banks without branches could pass some of that saving on.
- Banking at any hour, with instant transfers through NPSB and payments through Bangla QR.
- More competition for traditional banks, pushing them to improve slow apps and cut fees.
What else is shaping the future?
Bangla QR and person-to-person transfers
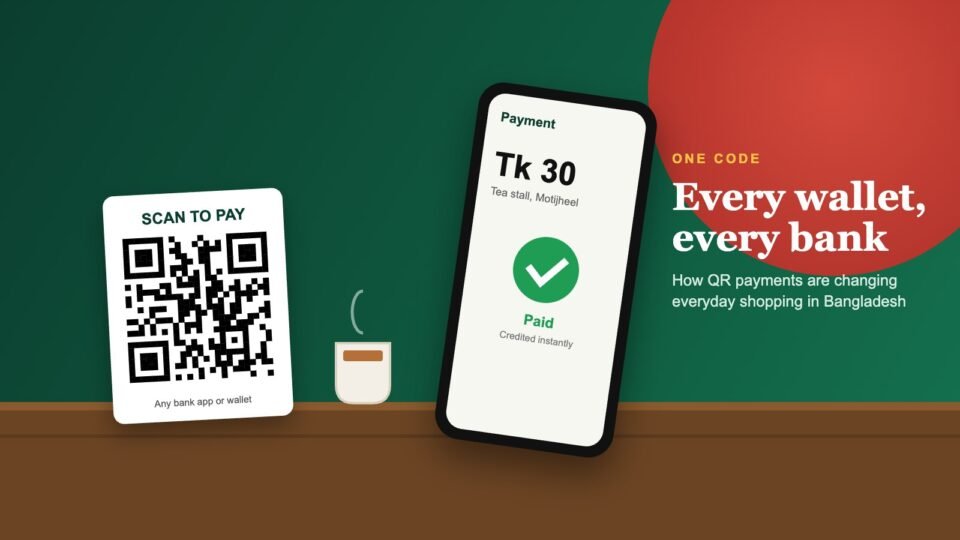
Since July 2026, one Bangla QR code at a shop accepts payments from any bank app or mobile wallet. Merchants get paid instantly, customers pay no fee, and person-to-person QR transfers between banks and wallets were set to start on 1 November 2026. We explain this in how Bangla QR is changing everyday transactions. A common payment rail means a new digital bank does not need its own merchant network to be useful from day one.
Traditional banks fighting back
Some banks have already built strong apps. BRAC Bank’s Astha has over 12 lakh users and handles about Tk 20,000 crore a month, according to figures shared with The Daily Star, and EBL, MTB and City Bank have growing digital platforms. But many others are held back by old systems and bad loans, as we found in why traditional banks are struggling to go digital.
New payment players
Payment service providers are multiplying. Banglalink received a licence in August 2026 for Mukto Pay, covering transfers, merchant and bill payments, and salary disbursement, VEON said. Pathao Pay, iPay and Pocket are already in the market. Some of these wallets may become the front door to digital banks’ savings and loan products.
What could hold digital banking back?
- Trust. The collapse of weak banks, including the 2026 merger of five troubled Islamic banks into Sammilito Islami Bank, has made depositors cautious about where they keep their money.
- Cybersecurity. An earlier BIBM study rated 52% of banks at high cyber risk and counted up to 630 attacks a day. A branchless bank’s whole business depends on its systems being safe.
- Digital literacy. The BIBM study named a knowledge gap as the biggest barrier to adoption. Many people, especially older and rural customers, still need help with apps.
- Bad loans in the system. Defaulted loans were 32.78% of all loans at the end of June 2026, Dhaka Tribune reported. Lending based on digital data must not repeat the mistakes of the past.
- Slow and uncertain regulation. The first round of digital bank licences produced no working bank in three years.
- Who pays for free payments. With Bangla QR’s interchange fee at zero, the wallet Upay said it loses Tk 5 to Tk 8 per Tk 1,000 when its customers pay at another operator’s QR, The Financial Express reported. Digital services must find a sustainable business model.
What to watch next
| Milestone | Why it matters |
|---|---|
| Person-to-person Bangla QR transfers (from 1 November 2026) | Makes sending money between any bank and wallet as easy as scanning a code |
| Bangla QR dispute rules (1 December 2026) | Gives customers a clear way to fix wrong or fraudulent payments |
| Full licences for the five digital banks | The moment Bangladesh gets its first working branchless banks |
| Open-end fund and other services moving online | Shows whether savings and investment, not just payments, go digital |
| Bangladesh Bank’s 2027 target | 75% of retail transactions digital |
What does this mean for you?
- Treat your bank’s app as seriously as its branch when you choose a bank.
- When digital banks open, check that the bank holds a full Bangladesh Bank licence before you deposit money.
- Keep your digital payment history clean and regular; it may become the basis for loans.
- Never share your PIN or OTP, whatever the app or caller claims.
Back to Sumi
For now, Sumi takes payments through a Bangla QR sticker printed with her page name. “My customers pay from whatever app they have,” she says. “When a bank lets me open an account from my phone and gives me a small loan for stock, I will be the first to sign up.”
Frequently asked questions
Are there any digital banks operating in Bangladesh?
Not yet. Five received initial approval in September 2026, but they must meet more conditions before getting full licences and opening.
What is the difference between a digital bank and bKash?
bKash is a mobile financial service, not a bank. A digital bank holds a full banking licence and can take deposits and give loans, but has no branches.
How much capital does a digital bank need?
Tk 300 crore in paid-up capital, and it must list on the stock market within five years of getting its licence.
Will digital banks be safe?
They will be regulated by Bangladesh Bank like other banks. Safety will depend on strong systems and customers protecting their PINs and OTPs.
What is Bangladesh Bank’s digital payment target?
At least 75% of retail transactions should be digital by 2027.
Key words explained
| Term | What it means |
|---|---|
| Digital bank | A licensed bank with no branches that serves customers through an app. |
| Letter of intent (LoI) | Initial approval; a full licence comes only after conditions are met. |
| MFS | Mobile financial service, such as bKash or Nagad. |
| PSP | Payment service provider, such as a licensed wallet that is not a bank. |
| e-KYC | Opening an account online with NID and photo verification. |
| Bangla QR | Bangladesh Bank’s single, shared QR payment code. |
| Paid-up capital | The money owners have actually put into a bank. |
How we reported this
We used Bangladesh Bank data reported by The Daily Star and UNB, BIBM studies reported by The Financial Express and The Business Standard, The Business Standard’s reports on digital bank approvals and the World Bank’s criticism, The Daily Star’s report on digital bank licensing rules, Dhaka Tribune’s report on defaulted loans, VEON’s announcement on Mukto Pay, and our own earlier coverage. What digital banks will offer is our assessment based on these sources, since none has yet launched. The featured image is an illustration made by Dhaka Debates.
Editor’s note: Sumi is illustrative, created to show the kind of customer digital banks aim to serve. She is not a real person. All data come from the published sources listed with this article.
Sources
- The Business Standard: 5 digital banks, including bKash and Robi-backed ventures, get BB approval · tbsnews.net
- The Daily Star: Digital bank licence window reopens · thedailystar.net
- The Business Standard: World Bank sees favouritism in digital bank licensing · tbsnews.net
- The Daily Star: App-based banking gains traction as customers go digital · thedailystar.net
- The Financial Express: 75pc of banking customers still excluded from digital services · today.thefinancialexpress.com.bd
- UNB: Bangla QR transactions surge nearly fivefold to Tk 143.54cr daily · unb.com.bd
- The Daily Star: One QR, every wallet · thedailystar.net
- The Business Standard: Majority of banks at high cyber risks, BIBM study · tbsnews.net
- Dhaka Tribune: Default loans in banking sector cross Tk6 lakh crore · dhakatribune.com
- VEON: Banglalink receives Bangladesh Bank approval to launch Mukto Pay · veon.com
- The Financial Express: Bangla QR misuse raises concerns over MFS sustainability · thefinancialexpress.com.bd