BEFTN or NPSB: Which Bank Transfer Is Faster?
NPSB sends money to another bank in seconds, any day of the week. BEFTN works in batches and stops on weekends and holidays. Here is how each one works, the limits and fees, and when you should still choose BEFTN or RTGS.

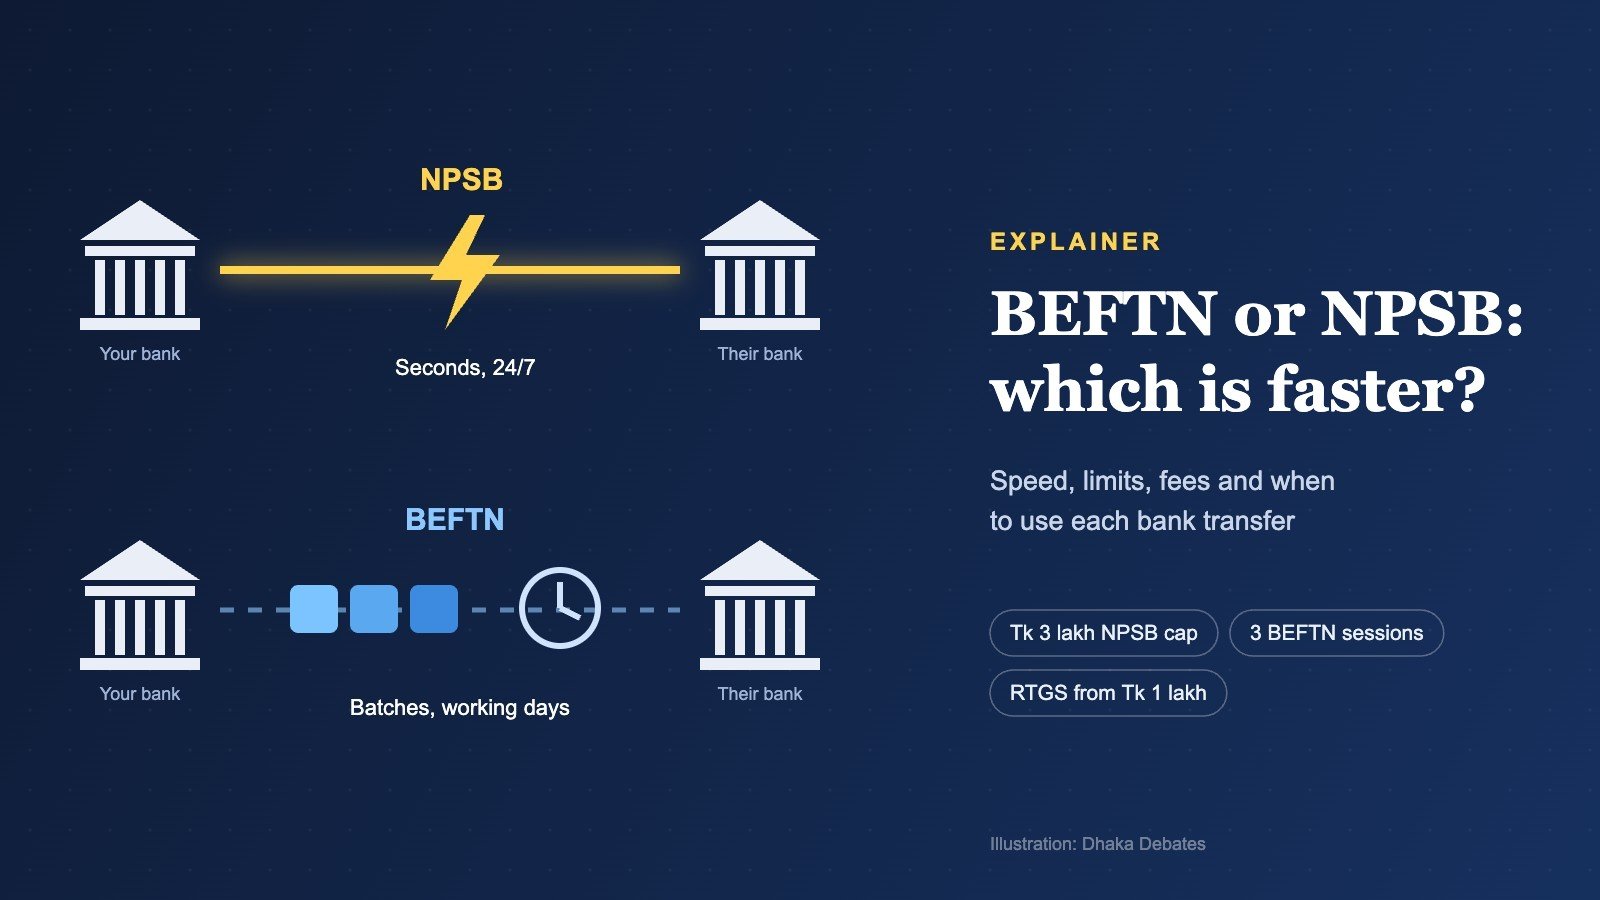
Short answer: NPSB is faster. An NPSB transfer from your bank app usually reaches the other bank account within seconds, and it works 24 hours a day, including Fridays, Saturdays and holidays. BEFTN works in batches. Money sent early on a working day often arrives the same day, but money sent in the afternoon, on a weekend or on a holiday waits for the next working day. NPSB has lower limits, though: Bangladesh Bank caps it at Tk 3 lakh per transfer and Tk 10 lakh a day for individuals, and many banks set even lower limits. For bigger amounts, BEFTN or RTGS is often the better choice.
Open almost any Bangladeshi bank app and tap “Fund Transfer” to another bank. You will usually see at least two choices: BEFTN and NPSB. Some apps also show RTGS. Most people pick one at random, or whichever the app shows first. Then they wonder why the money they sent on Thursday afternoon still has not arrived on Saturday.
This guide explains, in plain words, how BEFTN and NPSB work, why one is faster than the other, what each costs, how much you can send, and which one to use in common situations. For a deeper look at each system on its own, see our explainers on what BEFTN is and what NPSB is.
What is BEFTN?
BEFTN stands for Bangladesh Electronic Funds Transfer Network. Bangladesh Bank launched it in 2011 as the country’s first paperless system for sending money between banks, The Daily Star reported. Before BEFTN, moving money between banks usually meant writing a cheque and waiting for it to clear.
BEFTN handles two kinds of payments:
- Credit transfers: money pushed from one account to another, such as salaries, dividends, foreign remittances paid out to local accounts, and government allowances.
- Debit transfers: money pulled from your account with your permission, such as loan EMIs, insurance premiums and utility bills.
Much of the government’s salary, pension and social safety net payments still run through BEFTN. So do the monthly salaries of many private companies.
How does BEFTN work?
BEFTN is a batch system. Your bank does not send your payment the moment you press “Confirm”. Instead, it collects many payments, sends them to Bangladesh Bank in a bundle, and the central bank settles them together in fixed sessions.
Since November 2023, BEFTN has run on Bangladesh Bank’s “Nikash-BEFTN” system under the Bangladesh Automated Clearing House (BACH). According to The Daily Star, transactions in taka are processed in three sessions a day:
| Session | Time window |
|---|---|
| Session 1 | 12:00 am to 11:59 am |
| Session 2 | 12:00 pm to 2:59 pm |
| Session 3 | 3:00 pm to 11:59 pm |
The receiving bank must post the money, or return it if something is wrong, within the next two sessions. In practice, this means money sent in the morning of a working day often arrives the same afternoon. But each bank sets its own cut-off time for customers, and many banks stop taking same-day BEFTN requests around midday. Requests made after that, or on a Friday, Saturday or public holiday, are processed on the next working day.
What is NPSB?
NPSB stands for National Payment Switch Bangladesh. It is also run by Bangladesh Bank. NPSB is the reason you can use one bank’s debit card at another bank’s ATM, or pay with your card at a shop’s POS machine regardless of which bank owns the machine.
NPSB also runs the Internet Banking Fund Transfer service, often shown in apps as “IBFT” or simply “NPSB”. This is the part that matters for this guide. When you choose NPSB in your bank app, the payment is sent and approved one by one, in real time, rather than waiting for a batch.
How does NPSB work?
When you send money through NPSB, your bank sends a message to the switch, the switch passes it to the receiving bank, and the receiving bank checks the account and credits it straight away. The whole process normally takes seconds. Because it does not depend on batch sessions, it keeps working at night, on weekends and on holidays, as long as both banks’ systems are online.
NPSB has grown beyond banks too. Since November 2025, Bangladesh Bank has expanded interoperable transfers so that money can move between bank accounts and mobile wallets such as bKash, Nagad and Rocket through the national switch. We explain how this fits into the bigger picture in our story on whether Bangladesh can become South Asia’s next fintech hub.
BEFTN vs NPSB: which is faster?
NPSB is faster in almost every situation. The table below sums up the main differences.
| Feature | BEFTN | NPSB (internet banking transfer) |
|---|---|---|
| How it works | Batch: payments bundled and settled in sessions | Real time: each payment processed on its own |
| Typical speed | Same day if sent before your bank’s cut-off; otherwise next working day | Usually within seconds |
| Works on Friday, Saturday and holidays? | No; waits for the next working day | Yes, 24/7 (if both banks are online) |
| Bangladesh Bank limit for individuals | No central cap reported; banks set their own limits | Tk 3 lakh per transfer, Tk 10 lakh per day |
| Limit for businesses | Set by banks; widely used for bulk payroll | Tk 5 lakh per transfer, Tk 25 lakh per day |
| Typical fee | Often free or a small bank fee | Small bank fee, often around Tk 10 plus VAT |
| Bulk payments (salaries, dividends) | Yes, designed for this | Not designed for bulk |
| Debit payments (EMI, bills) | Yes | No |
| Best for | Large or non-urgent payments, payroll, recurring debits | Urgent everyday transfers up to the limit |
How much can you send with NPSB?
Bangladesh Bank sets the upper limits for interbank transfers through internet banking. According to The Daily Star, the central bank’s limits are:
| Customer type | Per transfer | Per day |
|---|---|---|
| Individual | Tk 3 lakh | Tk 10 lakh |
| Business | Tk 5 lakh | Tk 25 lakh |
Bangladesh Bank also removed the old rule that limited individuals to 10 interbank transfers a day and businesses to 20. But these are ceilings, not promises. Each bank can set lower limits inside its own app. For example, Islami Bank’s internet banking allows NPSB transfers of up to Tk 50,000 per transaction, according to payment company comparisons published this year. Check your own bank’s app or website for its current limit before you rely on NPSB for a large payment.
If your bank caps NPSB at Tk 50,000 and you need to send Tk 2 lakh, you would need four separate transfers. At Tk 11.50 each (Tk 10 plus 15% VAT), that is Tk 46 in fees (our calculation), assuming your daily limit allows it. In that case a single BEFTN transfer may be simpler, as long as you can wait a few hours.
How much do BEFTN and NPSB cost?
Fees are set by each bank within Bangladesh Bank’s rules, so they differ. In general:
- BEFTN: many banks charge nothing for BEFTN transfers from their apps, while some charge a small fee. Islami Bank, for example, lists Tk 10 per BEFTN transfer on its internet banking.
- NPSB: most banks charge a small fee per transfer, commonly around Tk 10 plus 15% VAT, so about Tk 11.50.
- RTGS: Bangladesh Bank allows banks to charge up to Tk 100 per RTGS transaction, according to Elevate Pay’s summary of central bank circulars.
- Bank to mobile wallet: moving money from a bank account to an MFS wallet through the national switch carries a small percentage fee, while moving money from a wallet to a bank costs more. Check your app before you confirm.
For most people, the difference in fees between BEFTN and NPSB is a few taka. The bigger difference is time. If you are paying a supplier on a Thursday evening, a Tk 11.50 NPSB fee is a small price for the money arriving in seconds rather than on Sunday.
What about RTGS?
RTGS stands for Real Time Gross Settlement. It is Bangladesh Bank’s system for large, urgent payments. Each payment is settled individually and immediately, like NPSB, but only during business hours on working days.
- Minimum: Tk 1 lakh for customer transfers in taka.
- Hours: customer taka transfers run from 10 am to 5 pm on working days. Between 4 pm and 5 pm, only online banking and app transfers are accepted, and banks may close earlier, according to Elevate Pay’s summary of Bangladesh Bank circulars.
- Fee: up to Tk 100 per transaction.
RTGS is growing fast. It handled 12.38 million transactions worth Tk 64.98 lakh crore in 2025, up 16% in number from 2024, The Financial Express reported. If you need to send Tk 5 lakh or Tk 50 lakh to another bank today, before the end of business, RTGS is the right tool.
| BEFTN | NPSB | RTGS | |
|---|---|---|---|
| Speed | Hours to next working day | Seconds | Minutes, during business hours |
| Days | Working days | Every day, 24/7 | Working days |
| Minimum | Set by bank | None centrally | Tk 1 lakh |
| Maximum (individual) | Set by bank | Tk 3 lakh per transfer; Tk 10 lakh a day | No central maximum reported |
| Fee | Free to small | Small (around Tk 10 + VAT) | Up to Tk 100 |
Which one should you use?
Here is a simple way to decide:
| Your situation | Best choice | Why |
|---|---|---|
| Sending Tk 20,000 rent to your landlord on a Friday | NPSB | Arrives in seconds; BEFTN would wait until Sunday |
| Paying a supplier Tk 80,000 on a weekday morning, no rush | BEFTN or NPSB | BEFTN will likely arrive the same day and may be free; NPSB if within your bank’s limit and you want it now |
| Sending Tk 4 lakh today for a property booking | RTGS | Above NPSB’s Tk 3 lakh per-transfer cap; RTGS settles the same day |
| Paying 50 staff salaries | BEFTN | Built for bulk payments; your bank’s corporate platform handles it |
| Setting up a monthly loan EMI to be taken from your account | BEFTN (debit) | NPSB does not handle automatic debits |
| Emergency hospital payment at night | NPSB | Only option that works at night and on holidays |
| Sending Tk 15 lakh to another bank | RTGS | Above NPSB’s daily cap |
A worked example: the Thursday rent problem
Tanjila, a 31-year-old teacher in Uttara, needs to pay Tk 18,000 rent by Friday. Her landlord banks with a different bank. On Thursday at 4 pm, after school, she opens her bank app.
- If she picks BEFTN: it is past her bank’s same-day cut-off, and Friday and Saturday are not working days. The payment is processed on Sunday. Her landlord sees it on Sunday, two days late.
- If she picks NPSB: the money arrives in her landlord’s account within seconds. She pays about Tk 11.50 in fees, if her bank charges Tk 10 plus VAT.
For Tanjila, NPSB is clearly the better choice. If she had paid on Wednesday morning, BEFTN would probably have worked just as well and might have been free.
Why might an NPSB transfer be delayed?
NPSB is normally instant, but not always. Common reasons for delays or failures include:
- The receiving bank’s system is down: some banks run maintenance at night or have outages. Your app may show the transfer as pending.
- Wrong account details: an incorrect account number or account name can cause the transfer to fail and the money to be returned.
- Your bank’s limit: if you go over your bank’s per-transfer or daily limit, the app will block the transfer.
- Special restrictions: Bangladesh Bank can pause services. Before the national election in February 2026, it suspended person-to-person NPSB internet banking transfers for 96 hours to prevent vote buying, The Daily Star reported.
If an NPSB transfer shows as failed or pending for a long time, do not send it again straight away. Check your account balance and the transaction history first, then contact your bank’s call centre with the transaction reference. Sending twice can leave you chasing a refund.
Why might a BEFTN transfer be delayed?
- Timing: sending after your bank’s cut-off or before a weekend or holiday is the most common reason.
- Wrong routing number: BEFTN uses a 9-digit routing number that identifies the bank and branch. One wrong digit can delay the payment or send it to the wrong branch.
- Name mismatch: if the name you entered does not match the account, the receiving bank may return the money.
- Holiday schedules: during long holidays such as Eid, Bangladesh Bank sometimes keeps BEFTN and RTGS open in limited form for a day or two, and announces special hours. Check the news before a holiday if a payment is urgent.
How do you choose NPSB or BEFTN in your bank app?
Every app looks a little different, but the steps are usually similar:
- Log in to your bank’s app or internet banking.
- Choose “Fund Transfer” and then “Other Bank” or “Interbank”.
- Pick the transfer type: NPSB (sometimes “Instant” or “IBFT”), BEFTN or RTGS.
- Add the beneficiary: name, account number and bank. For BEFTN and RTGS you may also need the branch or routing number. For NPSB, a card number may sometimes be used instead of an account number.
- Enter the amount and check the fee shown on screen.
- Confirm with your OTP or PIN. Never share this code with anyone.
- Save or screenshot the transaction reference until the receiver confirms.
Many banks ask you to add a new beneficiary and then wait a few hours before you can send large amounts to them. This is a safety feature against fraud. If you need to pay someone new urgently, add them as a beneficiary well before the day.
Is NPSB safe?
NPSB is run by Bangladesh Bank and is as safe as your bank’s app. The main risk is not the system itself but fraud: someone tricking you into sending money, or stealing your login and OTP. Because NPSB is instant, money sent to a fraudster can be gone before you notice. Take these simple steps:
- Double-check the account name shown before you confirm.
- Never share your PIN, password or OTP, even with someone who says they are from your bank.
- Be careful with “urgent” requests by phone or social media, even from people you know.
- Report any wrong or suspicious transfer to your bank at once.
What is changing next?
Bangladesh Bank is building an Interoperable Instant Payment System (IIPS) on top of NPSB. It was introduced in November 2025, and the central bank wants every bank, mobile wallet and financial institution connected by July 2027, Bonik Barta reported. Person-to-person Bangla QR payments, planned from November 2026, will also let you send money to anyone by scanning their personal QR code, across banks and wallets. Over time, instant transfers are likely to become the normal way to pay, and batch transfers like BEFTN will be used mainly for bulk payments and automatic debits. Read more in our guides to Bangla QR payments and how payment gateways work in Bangladesh.
If you are still choosing a bank, check how easy its app makes NPSB transfers and what limits it sets. Our guide to choosing your first bank account covers what to look for, and our feature on why traditional banks struggle to go digital explains why some apps are still hard to use.
Frequently asked questions
Is NPSB faster than BEFTN?
Yes. NPSB transfers usually arrive within seconds, 24/7. BEFTN works in batches on working days and can take until the next working day.
Does BEFTN work on Friday and Saturday?
No. Requests made on a Friday, Saturday or public holiday are processed on the next working day, except when Bangladesh Bank announces special holiday hours.
What is the NPSB transfer limit?
Bangladesh Bank’s ceiling for individuals is Tk 3 lakh per transfer and Tk 10 lakh per day. For businesses it is Tk 5 lakh per transfer and Tk 25 lakh per day. Your bank may set lower limits.
How long does BEFTN take?
If you send it before your bank’s cut-off on a working day, it often arrives the same day. Otherwise it arrives on the next working day. The receiving bank must post or return it within two settlement sessions.
Which is cheaper, BEFTN or NPSB?
BEFTN is often free or very cheap. NPSB usually costs around Tk 10 plus VAT per transfer. Fees vary by bank, so check your app.
Can I send money from my bank to bKash or Nagad through NPSB?
Yes, many banks now allow transfers to mobile wallets through the national switch. A small fee applies, and the option depends on your bank’s app.
When should I use RTGS instead?
Use RTGS for Tk 1 lakh or more when the money must arrive the same working day, especially above NPSB’s limits. It costs up to Tk 100.
Key words explained
| Term | What it means |
|---|---|
| BEFTN | Bangladesh Electronic Funds Transfer Network: Bangladesh Bank’s batch system for sending and collecting money between banks. |
| NPSB | National Payment Switch Bangladesh: the central switch for cards, ATMs and instant interbank transfers. |
| IBFT | Internet Banking Fund Transfer: the instant interbank transfer service that runs on NPSB. |
| RTGS | Real Time Gross Settlement: Bangladesh Bank’s system for large, urgent payments during business hours. |
| BACH | Bangladesh Automated Clearing House: covers cheque clearing (BACPS) and BEFTN. |
| Batch processing | Collecting many payments and settling them together at set times. |
| Cut-off time | The latest time a bank accepts a request for processing on the same day. |
| Routing number | A 9-digit code that identifies a bank branch for BEFTN and RTGS. |
| Beneficiary | The person or business receiving the money. |
How we reported this
We used Bangladesh Bank rules as reported by The Daily Star, The Financial Express and The Business Standard, and summaries of central bank circulars published by payment companies Elevate Pay and nsave. Session times, limits and holiday arrangements come from those reports. Bank-level fees and limits, such as Islami Bank’s, are examples from published comparisons and may have changed; always check your own bank’s current charges. Fee totals marked “our calculation” are our own arithmetic. We did not make test transfers, so the speeds described are based on how each system is designed and on published guidance.
Editor’s note: Tanjila is an illustrative example created for this guide, not a real person.
Sources
- The Daily Star: Electronic fund transfers thru Nikash-BEFTN software · images.thedailystar.net
- The Daily Star: Internet banking cap on number of fund transfers withdrawn · online92.thedailystar.net
- The Daily Star: NPSB transfers to remain suspended for 96 hours · thedailystar.net
- The Business Standard: Bangladesh Bank keeps BACH and RTGS services open during Eid holidays · tbsnews.net
- The Financial Express: RTGS crosses million monthly transaction mark in 2025 · today.thefinancialexpress.com.bd
- Bonik Barta: BB governor says interoperable transaction to go live by July 2027 · en.bonikbarta.com
- Elevate Pay: BEFTN, NPSB and RTGS in Bangladesh · elevatepay.co
- nsave: BEFTN explained · nsave.com
- nsave: NPSB Bangladesh explained · nsave.com